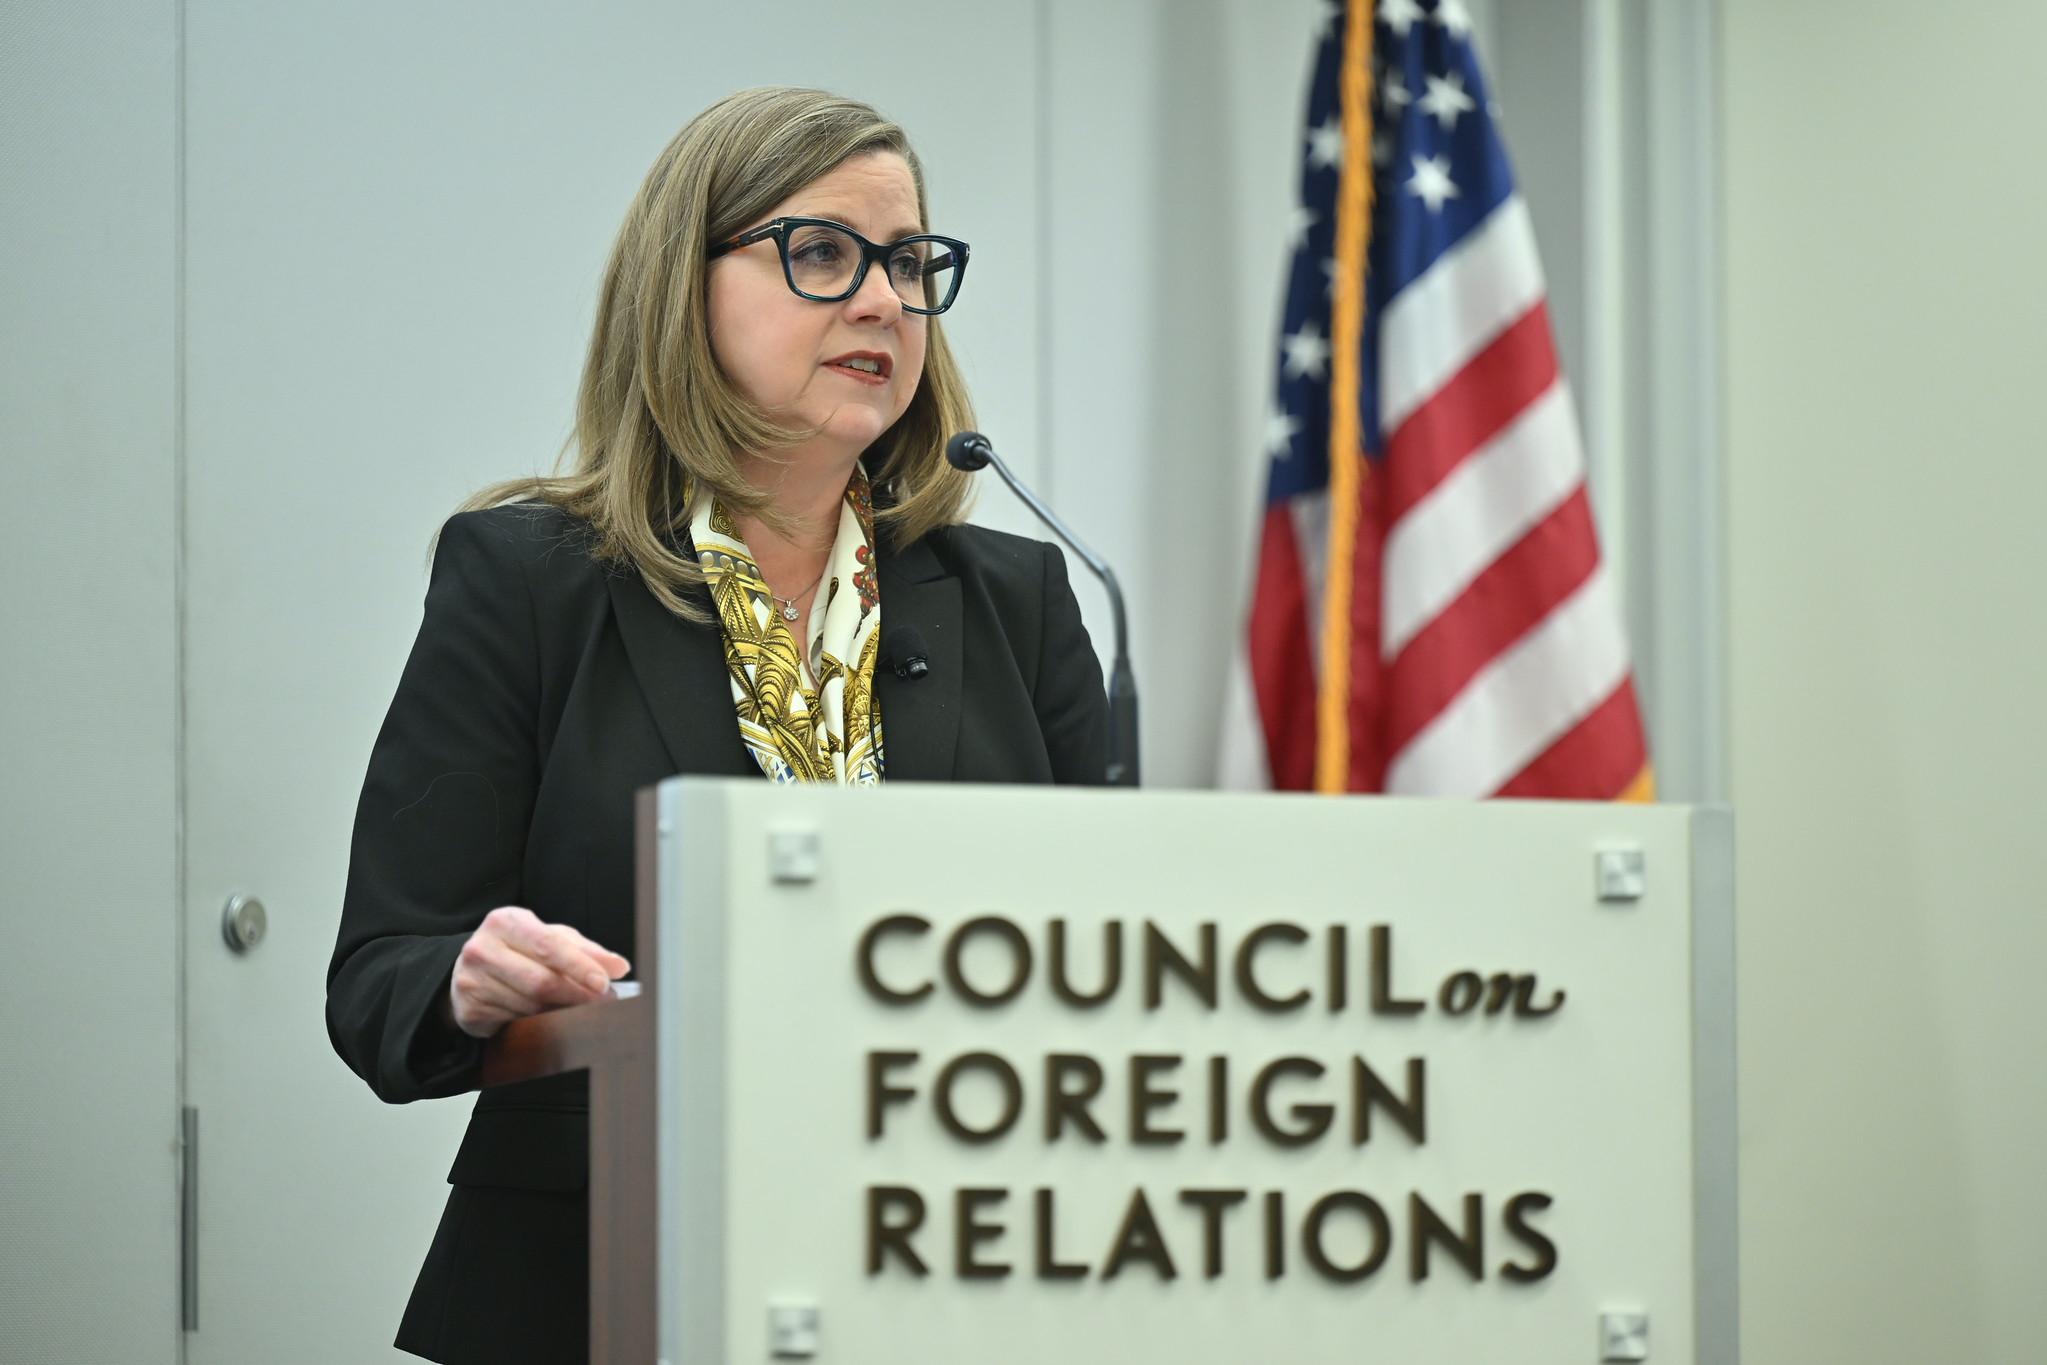
Federal Reserve Bank of Dallas President Lorie Logan called Friday for the U.S. central bank to establish a clear operational split between assets acquired for emergency market functioning and those held for monetary policy.
Logan, speaking at a bank funding conference co-hosted by the Dallas Fed, proposed that the Federal Open Market Committee hold any securities purchased for market-functioning purposes in a distinct account with an explicit commitment to sell them as quickly as possible once market stability is restored.
The segregation would prevent temporary liquidity interventions from inadvertently signaling prolonged monetary accommodation. Market-functioning purchases during acute stress—such as the initial COVID-19 pandemic phase—aim to unfreeze credit markets and restore normal functioning, not to stimulate aggregate demand or influence inflation expectations.
Monetary policy operations like quantitative easing or tightening, by contrast, are explicitly designed to shift economic conditions through balance sheet adjustments. Logan's proposal draws a sharper line between these distinct objectives.
From a fixed-income lens, operational clarity carries real market consequences. Bond investors constantly parse Fed balance sheet moves for clues about long-term policy stance, directly impacting duration positioning and yield curve expectations. A transparent mechanism for unwinding emergency asset purchases would help prevent the market from misinterpreting temporary liquidity actions as concealed stimulus, reducing noise in yield reactions and spread behavior.
Logan's call reflects an unresolved debate within the Fed about optimal balance sheet architecture following periods of massive asset accumulation. A formal FOMC commitment to separate accounting and rapid divestment would set a new operational precedent for the next crisis, clarifying the boundary between emergency intervention and policy intent.


