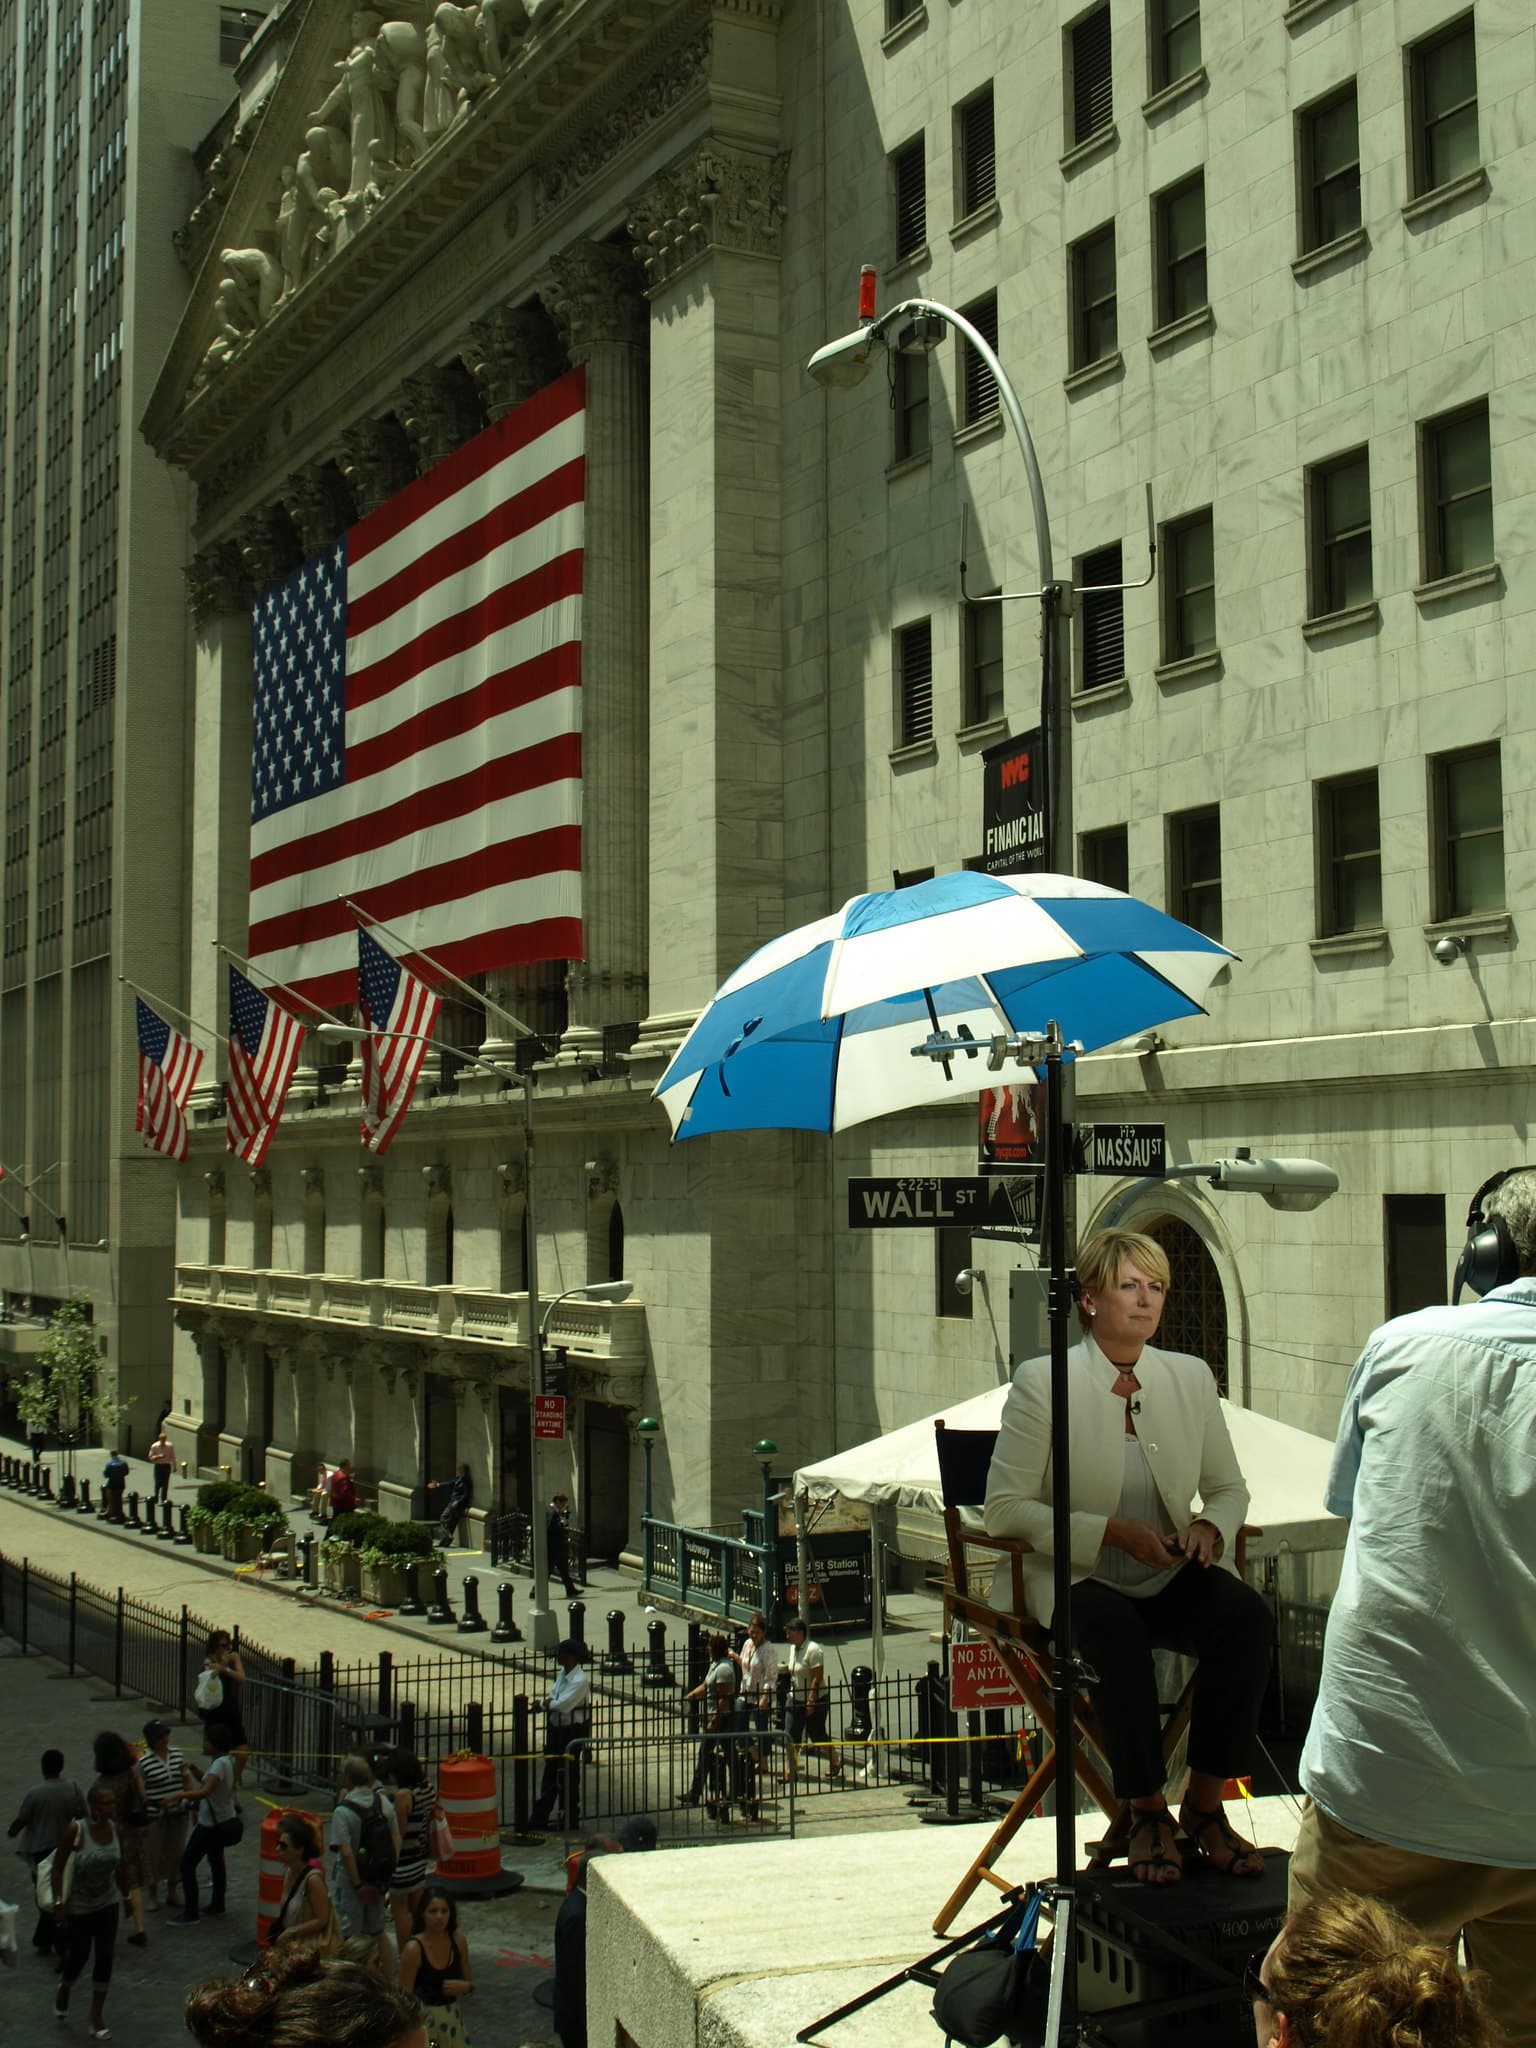
NEW YORK — The Federal Reserve raised interest rates by 25 basis points to a 3.75%-4% target range, marking its first hike in three years and triggering a sharp selloff in equities. The Dow Jones Industrial Average fell 1.2%, or over 600 points, while the S&P 500 declined 0.4%. The Nasdaq Composite finished flat.
The selloff intensified during Federal Reserve Chair Kevin Warsh's press conference. The Dow dropped to 1.6% at its worst point as traders interpreted Warsh's comments as signaling continued hawkish resolve. "Our predominant focus is on the price stability side of our mandate," Warsh said. "The plain fact is that inflation is too high and has been for too long."
The Fed's Summary of Economic Projections signaled at least one additional rate hike in 2026, extending the tightening cycle beyond investor expectations. Bond markets sold off sharply on the hawkish guidance. The 10-year Treasury yield topped 5%, its highest level since the financial crisis, weighing heavily on equity valuations.
August retail sales reaccelerated to 1.2%, exceeding expectations of 0.9% and reversing July's 0.5% decline. The stronger consumer spending data reinforced the Fed's view that inflation remains persistent and justifies further monetary restraint.
Crude oil prices remain elevated. Brent and West Texas Intermediate futures stayed above $100 per barrel, adding to inflation concerns and pressuring sentiment.
For equity investors, the message is stark: the Fed is not done tightening, and bond yields near 5% offer a genuine alternative to equities. Growth stocks and rate-sensitive sectors face sustained headwinds. Monitor the market's reaction to the Fed's future guidance and retail data as barometers of economic resilience—a weakening consumer or cooling inflation could prompt a pivot, but near-term momentum favors bonds over stocks.


