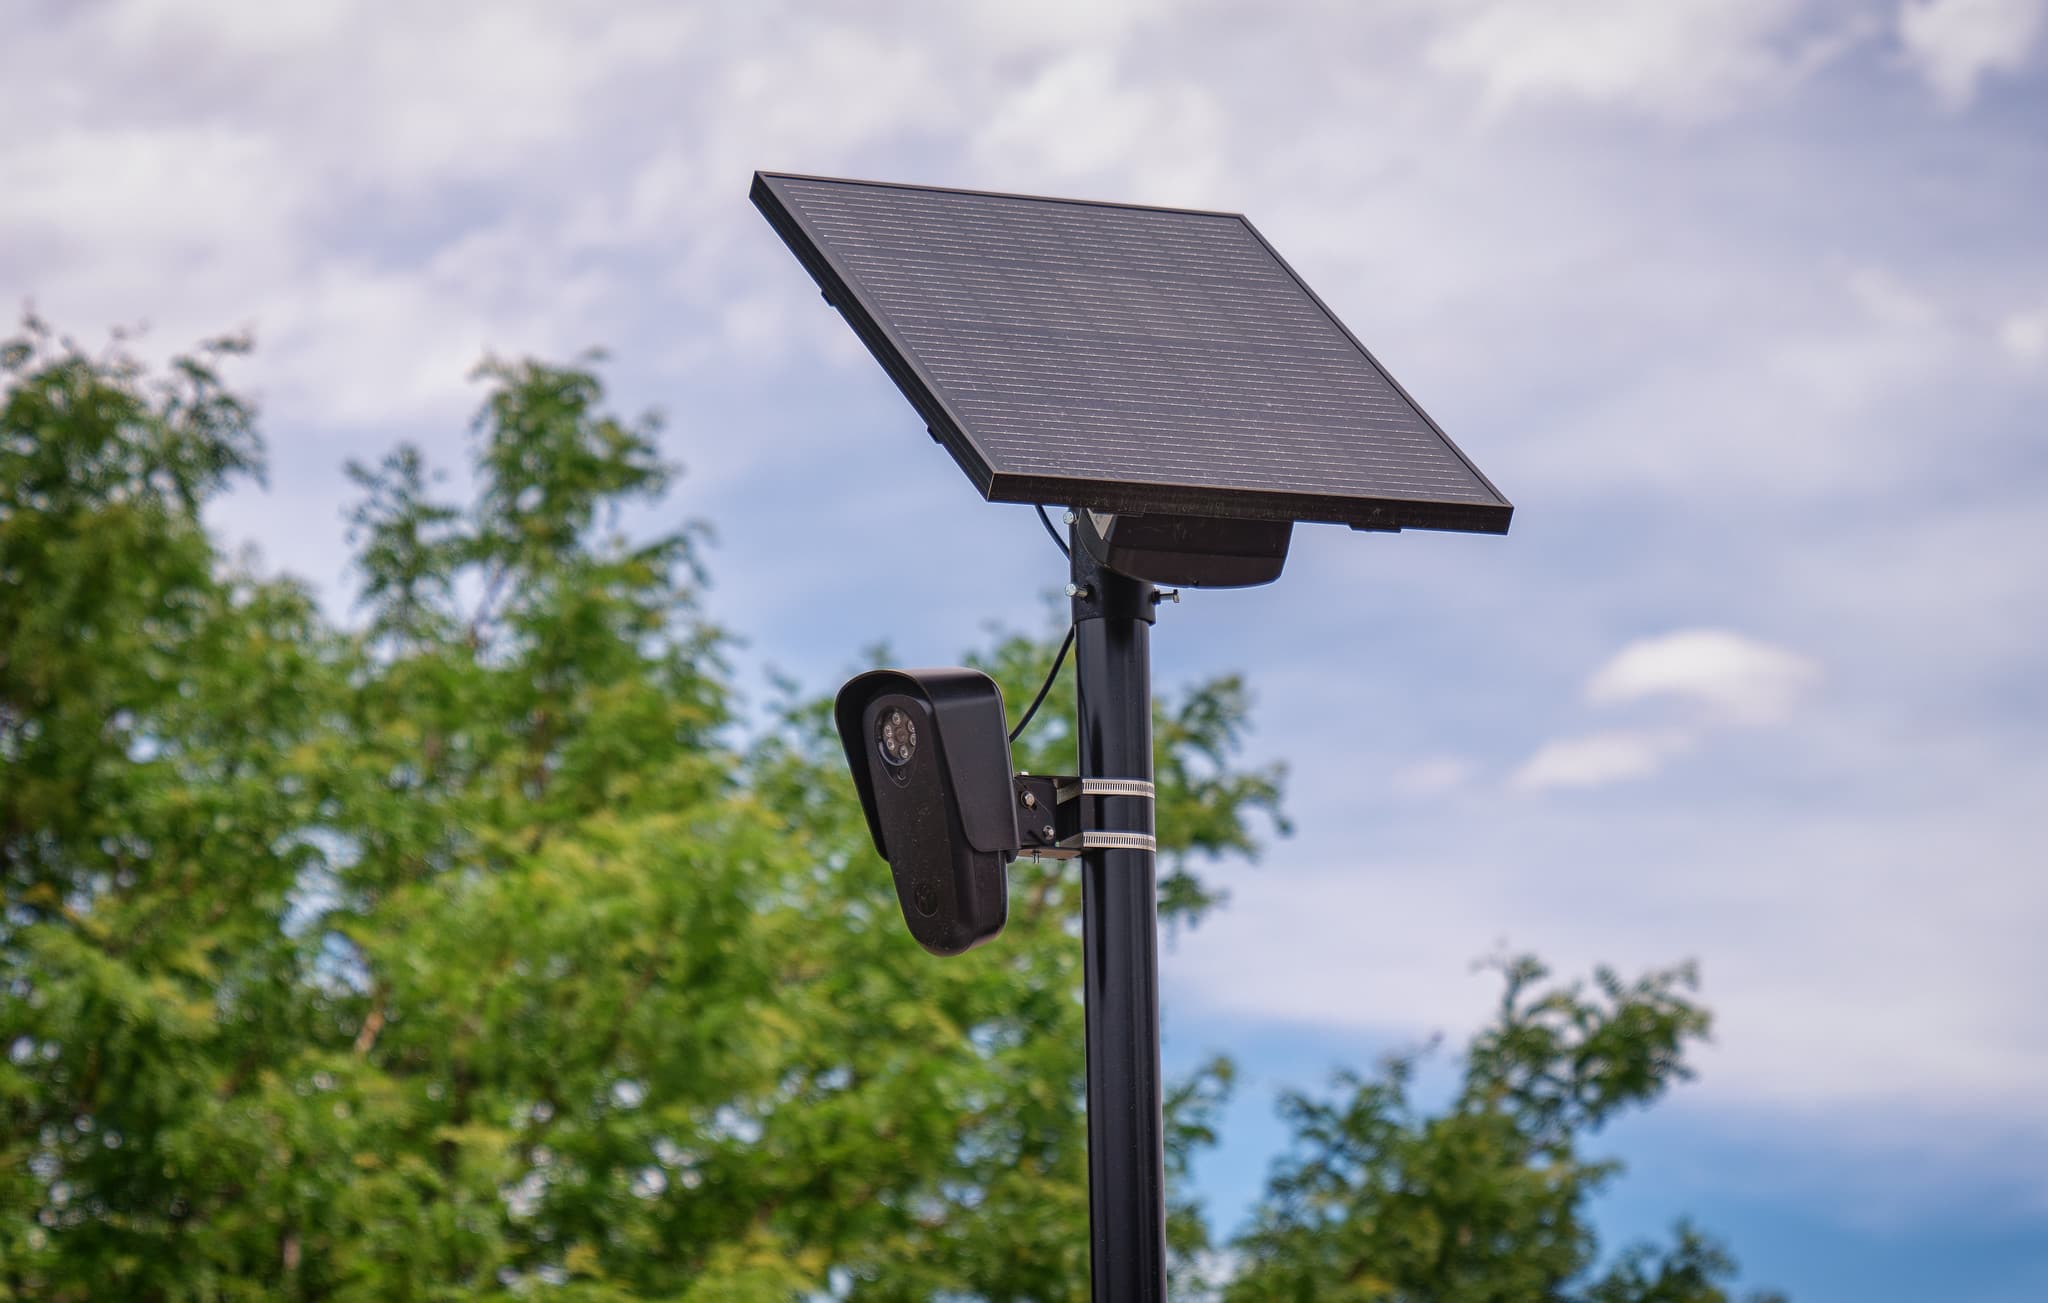
Flock Safety will lay off approximately 18 percent of its workforce as the AI-powered surveillance camera and license-plate reader company confronts mounting opposition from communities and lawmakers over data privacy and algorithmic bias concerns.
The job cuts eliminate hundreds of positions across the U.S. For fixed-income investors, the move underscores a material shift in how credit markets are pricing non-financial risk in the surveillance-technology sector. Companies facing sustained public opposition typically absorb higher compliance and legal costs while experiencing slower revenue adoption—both negative pressures on free cash flow generation and debt-service capacity.
The credit implications are already visible in sector spreads. Surveillance-tech vendors face widening yield premiums as bond investors demand compensation for regulatory uncertainty and potential contract losses at the municipal level. Several U.S. cities are reviewing existing Flock Safety deployments, with decisions expected in the coming months. These municipal reviews introduce near-term event risk and could reset expectations for the entire sector's long-term revenue stability.
For investors holding duration exposure to growth-stage tech firms, regulatory headwinds in AI deployment are raising volatility in earnings forecasts and credit quality assessments. Capital is rotating toward less contentious tech subsectors, compressing spreads there while pushing wider the yield premium required from vendors facing sustained policy resistance.